

Whilst going through the half year results of Chinese owned miner MMG last week I couldn’t shake the thought that big things are brewing… and I don’t mean a succulent kung pao chicken… I’m talking about a multi billion dollar mining deal.
MMG’s report and accompanied presentation was littered with words that spoke of an aggressive growth agenda. Despite generating US$1.7 billion (!) in after tax free cash flow for the HALF the company raised a further US$1.6 billion in June via the issue of US$800m of shares (at HK$8.88/sh - classic Chinese) and the issue of US$800m in zero coupon convertible bonds - which have a 1 year duration (!) and a HK$10.21 conversion price. They now have an arsenal of US$3.1bn in cash (up from US$0.3bn at 31-Dec) and operations that should print north of US$3.5bn pa based on current commodity prices. Debt (including the recently issued convertibles) sits at just US$3.7bn.
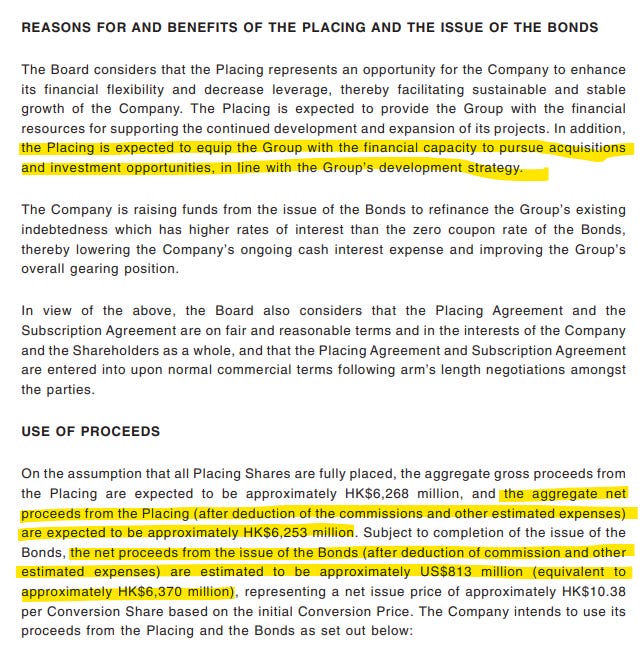
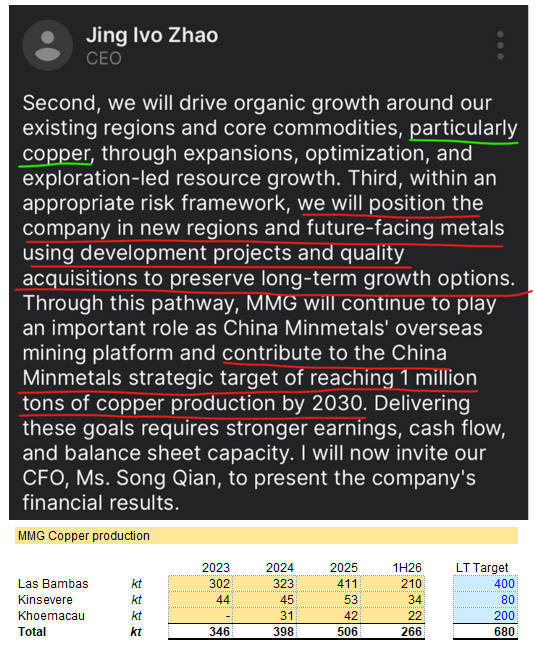
MMG has been quite active in the M&A space of late acquiring the Khoemacau copper mine in Botswana in early 2024 for ~US$2bn and last year agreeing to acquire Anglo American’s nickel business in Brazil for US$500m.. (though this one is still yet to close with regulators.). They have stated intentions to produce 1 million tonnes of copper per year by 2030… and if you look at where that is likely to come from… a lot is driven by M&A.
What MMG could be up to intrigued me to go look at some other major Chinese mining companies such as Jiangxi Copper, CMOC and Zijin Mining. I have fond memories of buying SolGold last year under 10p/sh as it lagged peers and was a clear M&A target from major shareholder Jiangxi… and sure enough in the second half of last year Jiangxi made multiple bids for the company before successfully sealing a deal at 28p/sh (~US$1.2bn). Like MMG - Jiangxi, CMOC and Zijin all look to have very strong balance sheets and operations that are oozing cash flow… and they all appear to have a mandate to secure resources to meet China’s national objectives… especially in copper which is one commodity China arguably doesn’t have a stranglehold on…yet. With so many Chinese companies hungry for copper deals.. lets see if we can’t identify which target would make for a succulent Chinese meal.
Potential targets
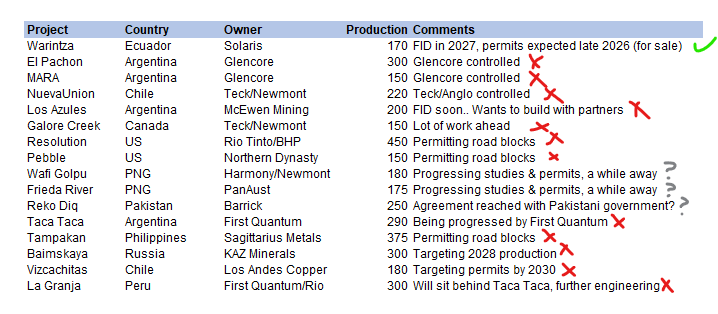
I must confess my first thought on acquisition targets was Solaris’s Warintza project and this was solely given my experience last year with SolGold and the very similar set up I see ahead. I ran a quick screen for projects with production targets over 150ktpa of copper that would move the dial for these major Chinese miners and were close to a position to hit FID. As you can see from the project list - a lot are either locked up by major western miners, are in “unfriendly” jurisdictions for the Chinese (like the US or Canada) or are a ways a way from production.. either due to permitting issues or engineering challenges.
The Solgold similarities
Around 2022 the Canadian government began placing far more scrutiny on M&A transactions that involved Chinese enterprises and even began interfering and blocking certain deals.. even though the location of these mining projects were outside of Canada. They were able to do this because the companies that owned the projects were Canadian domiciled. Chengze Lithium was blocked trying to take out Lithium Chile (Chile) and Ultra lithium (Argentina), Zijin was blocked from buying Peruvian project La Arena from Pan American silver… and Zijin was even blocked from taking a 15% stake of Solaris (Ecuador) - more on that later.
Solgold - which was an exploration company that had discovered the giant Cascabel copper/gold mine in Ecuador and had progressed it as far as the companies technical capabilities warranted - was looking to find a buyer to progress its project. With BHP and Newcrest - two early substantial shareholders - cooling on the idea of building a mine in Ecuador.. they identified Chinese capital as the next most likely buyer.
Solgold PLC was a UK incorporated company with both a London and Toronto listing. Cascabel was owned in part by Solgold PLC but also in part (15%) by Solgold Canada Inc. In 2025 - in response to the hostilities the Canadian government had shown toward Chinese mining deals - that 15% was transferred from Solgold Canada Inc to a Swiss subsidiary. Also in June 2025 the company delisted from the TSX, employees were moved to Europe and finally in August 2025 Solgold moved its tax domicile to Switzerland. Three months later came Jiangxi’s first bid and the rest is history.
Now for Solaris - who I mentioned above were blocked from the Canadian government in 2024 from selling a 15% stake in the company to Zijin Mining.. they have gone through a very similar playbook. In late 2024 Solaris announced that it was moving its headquarters to Switzerland. The company installed new Swiss based management including new CEO Matthew Rowlinson - an ex Glencore M&A specialist. It opened an office in Zug and replaced various directors with Swiss based personnel. And it changed its tax domicile from Canada to Switzerland. But an important differentiation is that it has remained Canadian incorporated...
Current state
After relocating to Switzerland at the start of 2025 Solaris did a US$200m gold stream on Warintza with Royal Gold in May 2025.. which was staged as US$100m upfront, US$50m upon PFS publication and US$50m a year after close. This gave the company adequate funding to progress the Warintza project through permitting and engineering stages and toward a decision to mine.
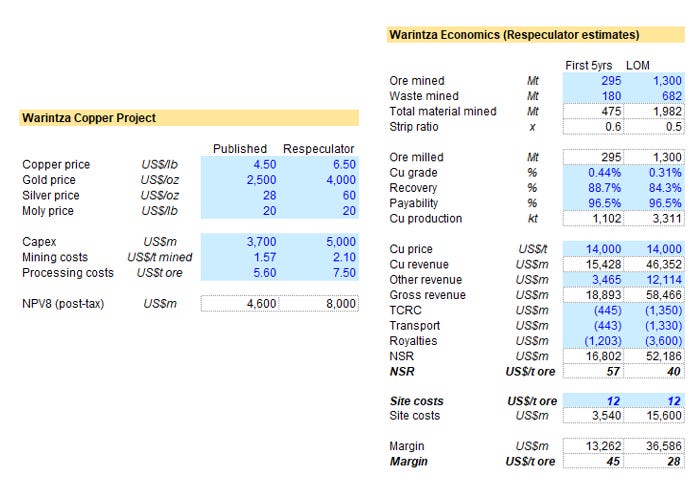
In November 2025 Solaris published a PFS on the Warintza project - showing a highly attractive project with US$3.7bn initial capital, annual EBITDA (at $4.50/lb copper) of US$1.9bn per year for the first 5 years and an NPV (at $4.50 copper) of US$4.6bn with a 26% IRR.
In April 2026 Solaris achieved a major permitting milestone securing the EIA technical approval. The company says this approval significantly derisks the permitting process and that they now are expecting to be fully permitted by the end of 2026.
The company is now progressing toward a definitive feasibility study alongside completing the permitting process. The DFS is expected with permits before the end of the year… and the company is looking to FID Warintza in early 2027.
Economics
The Warintza project has many favourable mining characteristics. It has a low strip ratio (~0.5:1), is bulk tonnage (1.3bt reserve, ~3bt M&I resource.. 60mtpa of ore milled) and is in an area that is low altitude and has established infrastructure such as roads, electricity, water and port infrastructure.
The project also has access to good grading ore early in the mines life - with the first 5 years averaging 0.44% copper whilst the average over the mine life is 0.31%. This materially improves the early cash flows and financial metrics like payback period and IRR.
The companies PFS study done in November 2025 showed a US$4.6bn post tax NPV (8%). I have remodelled the study with the below changes and estimate that at current commodity prices and escalating opex and capex - the project could be worth closer to US$8bn NPV and the first 5 years may generate EBITDA margins of US$3bn pa.
Chinese Attractiveness
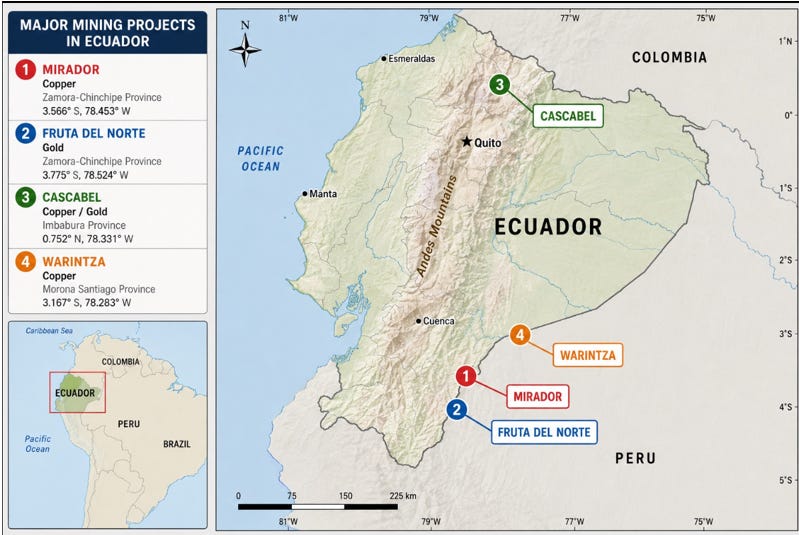
The economics of Warintza are highly attractive as shown above. In addition to this the project is relatively straightforward from a mining point of view. From a Chinese interest angle - the mine sits 40km away from the Chinese run Mirador copper mine and like Mirador Warintza will ship from the Ecuadorian coastline into the pacific which is an easy trade route to China. Ecuador is a party to China’s belt and road initiative. China has helped Ecuador finance and build various infrastructure projects such as hydroelectric power plants.
Risks
I must admit that I am not close to understanding the social licence to operate aspect of this project. And as we have seen with projects like Cobre Panama - when there is enough social opposition to these large projects they can get derailed. I do note there has been a history of opposition of this project by certain local groups. The company will be trucking some 800,000 tonnes of concentrate 300 kilometres from mine to port each year which will no doubt disturb many communities. The company appears confident post the EIA approval in April that they will receive full permits to mine by the end of the year… but this wont guarantee social acceptance and this remains a risk.
There is also risk that a bid doesn’t come and the company is either left standing at the altar or needs to finance something close to US$5bn in initial capital by themselves. Whilst there appears to be some capacity to do a large silver (or gold) stream and conventional debt I doubt the company can finance the project without some form of equity and with a capital bill approaching US$5bn and a market capitalisation of US$1.3bn this may represent a hurdle too large to climb. But I do like the early economics of this project and its simplicity - which allows for rapid payback and should therefore allow for a large debt facility and other non dilutive financing options (but ultimately i don’t think it gets to this stage).
The other key risk is the Canadian government somehow steps in the way of a transaction again.
Trade Set Up
Copper is making new all time highs.. and the copper miners ETF (COPX) just started playing catch up the past couple of weeks. But as you can see in the chart below.. Solaris (SLS.TO) and COPX have materially diverged since early July. It has not participated in the recent run up in copper price and just to catch up to this ETF means the stock must rerate +30%.
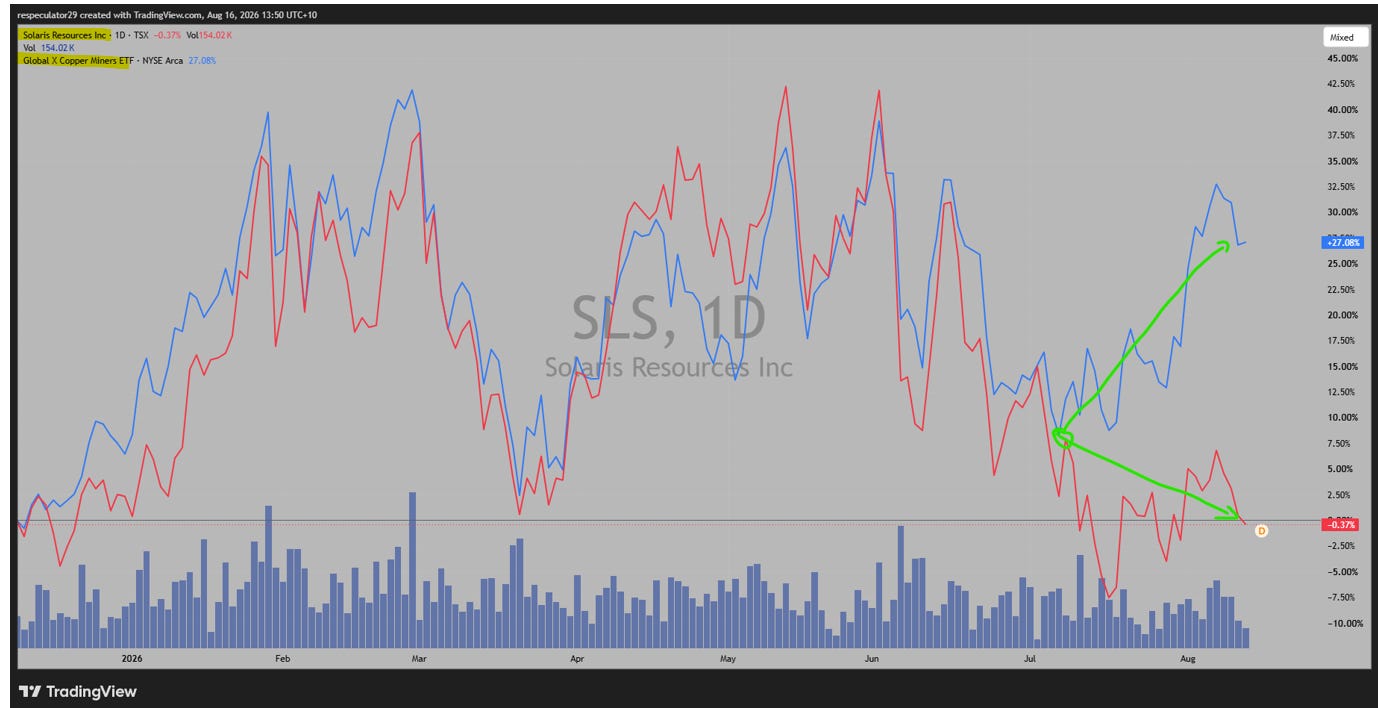
So I don’t mind this trade as a catch up trade on COPX to go along with the potential corporate activity that will potentially show itself later in the year as the company works through its DFS and permits.
SolGold rerated from ~$300m to US$1.2bn over just a few months once corporate activity was on the radar of investors. I’m not expecting a 4x like that given the existing valuation here… but with potentially an US$8bn NPV with up to date commodity prices, why couldn’t this sell for US$4bn (C$5.6bn) which is C$31/sh? Versus the C$11 share price that is a handsome return in my books for potentially something around a 6 month hold.
I’ve bought a small position and will assess as the company progresses the project and as I monitor the movements from some of the Chinese companies I think could be targeting this project.
Summary
Chinese miners appear to have a clear mandate to secure the commodities needed to meet China’s long term objectives. One commodity China doesn’t have a stranglehold on as yet is copper and this appears to be of particular focus when looking at commentary from the major Chinese mining companies.
Filtering for large scale (>150ktpa) copper projects that are not controlled by major western miners and are located in Chinese friendly jurisdictions shows there really are slim pickings. One large scale copper project that fits the bill and of which the Chinese have shown interest in previously is the Warintza project in Ecuador. In 2024 Zijin Mining tried to purchase a 15% stake before being blocked by the Canadian government.
Solaris, the owner of Warintza, all but has the project on a platter for the Chinese. It is in the final stages of engineering and permitting of the project before FID in early 2027. And it has followed a similar playbook of another Ecuadorian project that sold to the Chinese just last year in emigrating from Canada to Switzerland with regards to headquarters, management and tax domicile.
I’m of the view that Solaris will get sold to the Chinese over the next 6months… and with what I estimate as an NPV approaching US$8bn at todays copper price I wouldn’t be surprised if the project is sold for something close to US$4bn. This is a handsome return on the current US$1.35bn market cap.
As always - this isn’t investment advice, I’m a degenerate. Would love any thoughts/push back?
Respeculator
**Disclaimer - this is NOT intended as financial advice - before acting on any information, you should consider the appropriateness of the information provided to your financial situation and seek advice. Whilst every effort is made to ensure the accuracy of data provided there’s a good chance inaccuracies exist. This is opinion only.**
Solaris makes a lot of sense, also Tantakori (Regulus) makes sense. These two projects will be sold/built this cycle.
Makes a lot of sense as a takeout, especially since it's copper. I'm also holding Aurum which seems another inevitable takeout with similar characteristics, albeit gold. Will happily add a position in Solaris to my developer basket.