

I mentioned in my last note that coal miners were looking interesting once more on the back of huge Chinese mine supply cuts (safety related) in addition to a Qatari LNG force majeure extension and the fast approaching Northern Hemisphere winter where a scramble for molecules is no doubt going to ensue.
Initially I was going to follow up that note with a long spiel on the longer term fundamentals of coal, look at how the coal miners performed in the first half and take a closer look at some ways to play an increasing coal price. I still may do all of that but a fell down a bit of a rabbit hole on an incredibly torqued thermal coal miner which has a very colourful history, some very interesting recent shareholder and board room action and possibly a lot of future hidden value the market may be overlooking.
That company is A$125m/US$88m ASX listed thermal coal miner Terracom (TER.AX). The company that got caught up in botching their coal quality in 2020, had a run of near 10x during the 2022 coal run.. and famously paid out all the spoils of that last coal boom in dividends (~A$244m paid in FY23) whilst failing to leave enough cash in the coffers to pay the tax man!
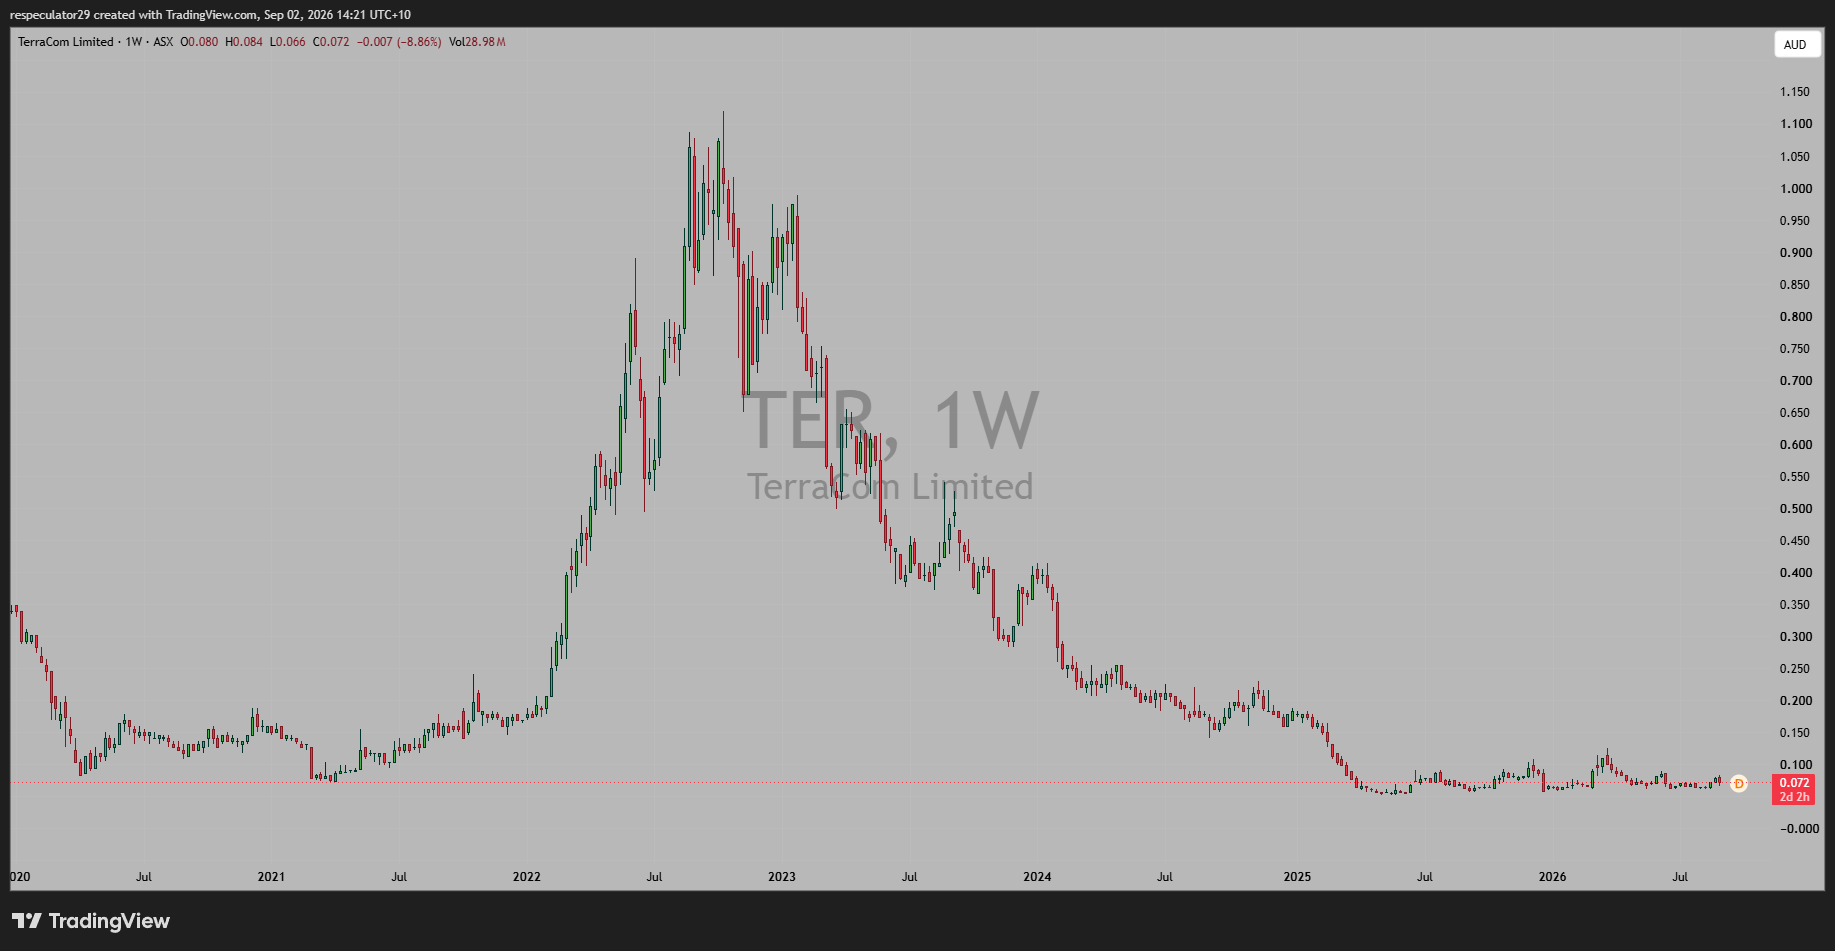
Today Terracom has producing Assets in Australia and South Africa and a potential growth option in Australia. I’m going to look at all these Assets, the balance sheet and the recent corporate shenanigans.
South African Mines
The South African mines held by Terracom (49% interest) were acquired through the A$175m acquisition of Universal Coal in 2020. In 2022 alone the South African mines sold 6.6Mt of coal for A$135m EBITDA (~A$20/t margin). But the margin is even better when you consider they make next to zero on the domestic sales to Eskom and this was ~5.1Mt of the ~6.6Mt of sales. The ~1.5Mt of export sales which made the lions share of the A$135m EBITDA was generating a healthy ~A$90/t margin.
The past few years there has been well publicised issues with South Africa’s rail provider Transnet. This has restricted Terracom’s export sales to effectively zero.. they couldn’t get the coal to market, so these Assets have returned nothing for Terracom. But recently Transnet has materially improved their logistics performance.
Terracom claim the South African operations are under “strategic review” which to me is code for up for sale. What can they get for them? I’m not sure… perhaps not the A$175m price they paid, but you do have some decent mines with logistic issues being resolved and a decent coal market. And Terracom after all is a A$125m company today.. but I’ll leave the South African Assets there, for the main game is the Australian mines.
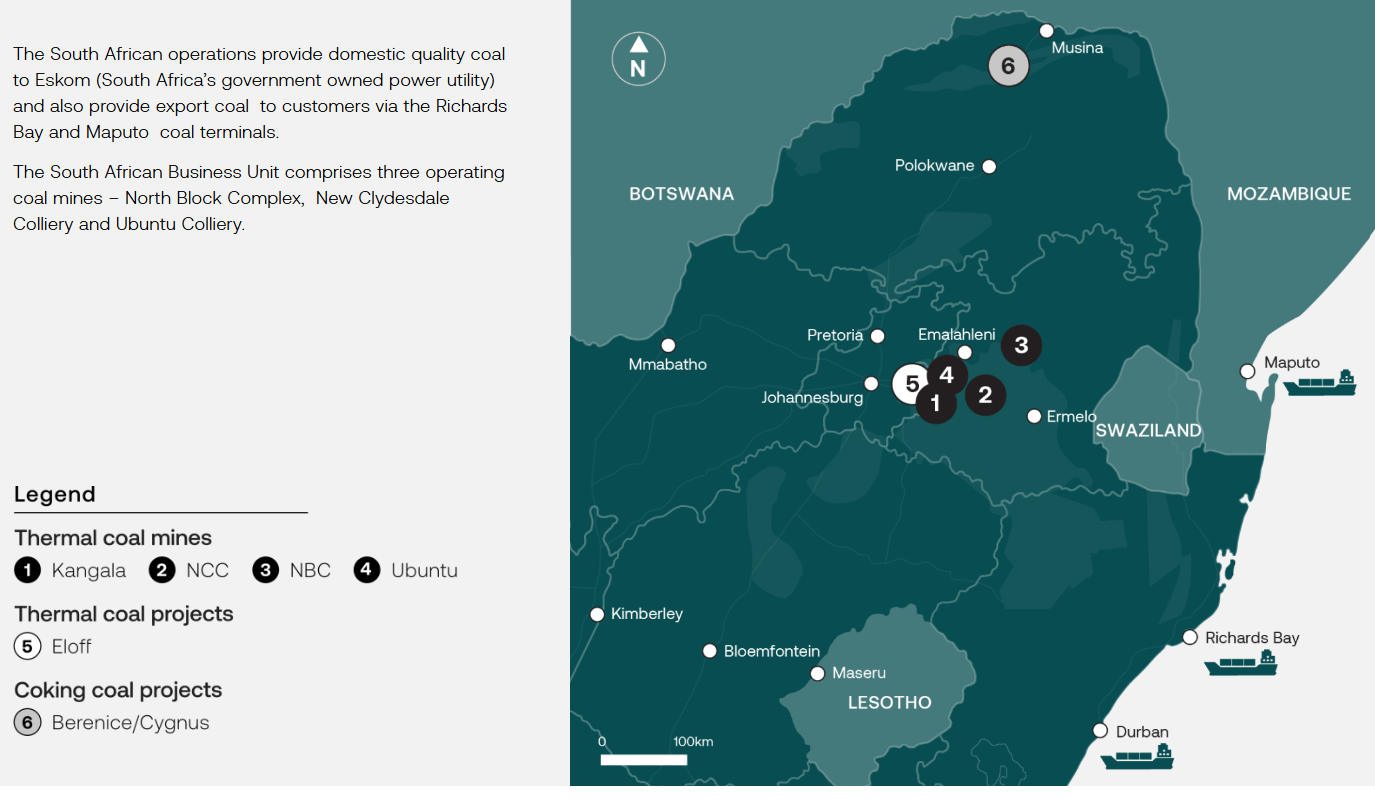
Current Australian Operations - Blair Athol
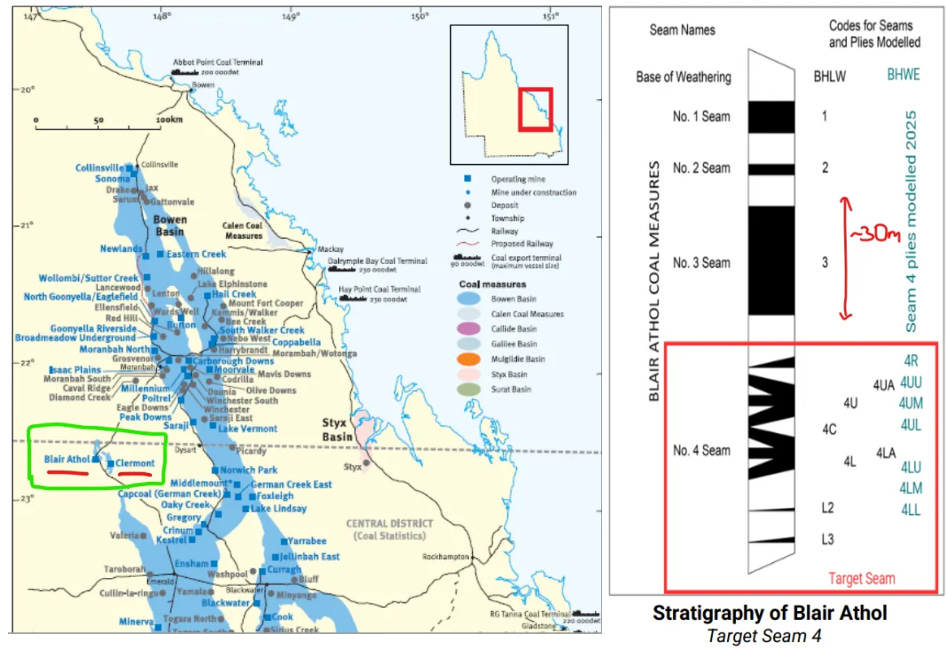
The Blair Athol mine was first developed by Rio Tinto/CRA in 1984. The mine was exceptionally productive as it used large scale open pit mining equipment including draglines and large excavators to take out the incredibly thick “No. 3” coal seam which averaged some 30 metres. The coal was low ash, high energy and the seam was continuous (lacked any real impurities in the interburden) so it was able to be sold directly without any washing/processing. Once extracted from the ground the coal was put onto trains via a dedicated train load out and taken to Dalrymple Bay in Mackay for loading into ships which took it to hungry Japanese power plants. In total the mine ran under Rio for 28 years from 1984 to 2012 and produced some 250 million tonnes of coal.
In the late 2000’s, as a replacement for Blair Athol, Rio Tinto built the neighbouring Clermont mine some 15km south East of Blair Athol… and to reduce capital costs Rio built an overland conveyor to take coal from Clermont to Blair Athol where it would use the Blair Athol train loading infrastructure to get the coal to port. As part of its planned exit from coal Rio sold Clermont - including the train load out at Blair Athol - to a consortium including Glencore in 2014… whilst it sold what remained of the Blair Athol mine (include the wash plant and dragline) to Terracom for $1 and some rehab obligations in 2017.
As I mentioned - Rio took out the fat seam No. 3 from Blair Athol and Terracom’s plan was/is to take out the upper seam No.4 from the mine you can see depicted below. This is a much smaller coal seam (<10m), deeper and has interburden that needs to be washed out via a CHPP (Rio eventually built a 350tph wash plant at Blair Athol to wash a small component of their No.3 seam coal which Terracom purchased with the mine).
You can see below a satellite image of the Clermont and Blair Athol operations with my annotations as to the infrastructure. Note that whilst the train load out (TLO) sits adjacent to Blair Athol mine it is owned and operated by Clermont. Terracom load trains via front end loaders on their own TLO (depicted below as BA TLO)… which is extremely inefficient.
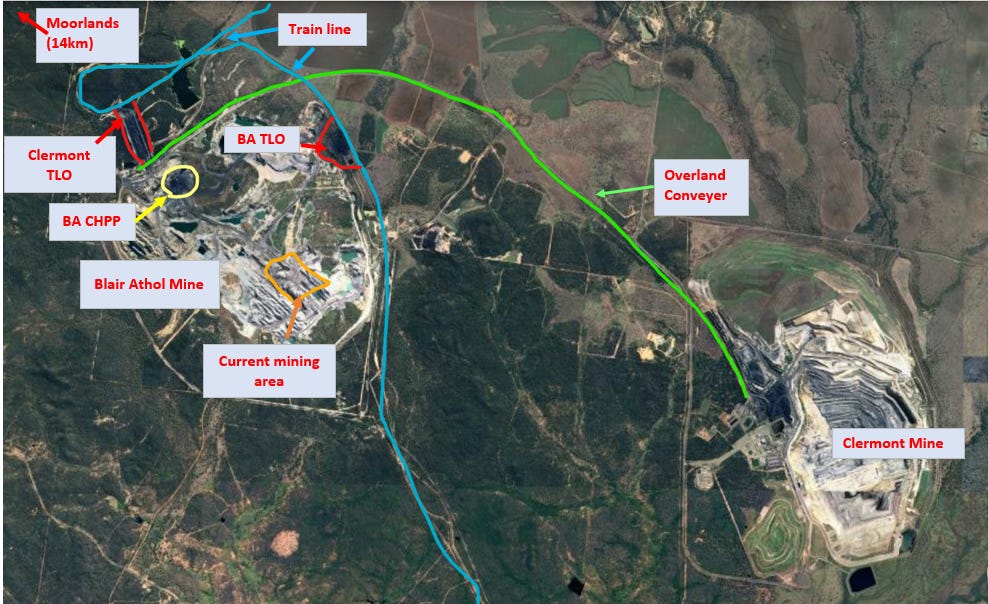
So today Terracom is attempting to mine 2mtpa out of the upper no.4 coal seam at Blair Athol and put it on a train with front end loaders. This makes for tough work… and a high cost / low margin mine. This gives it a lot of torque, but it also has some hidden value…
Future Australian Operations - Blair Athol + Moorlands + Clermont infrastructure
I mentioned above that Glencore and Co’s Clermont mine is being closed in the next 18months as it reaches end of life. And there’s a lot of infrastructure and workforce that could be of use to Blair Athol and Terracom upon closure - especially the TLO.
In addition to this infrastructure Terracom have a commercial arrangement (to be formalised) to develop the Moorlands coal project with Chinese party Wintime Energy. Moorlands sits 14km north west of Blair Athol, has 23 cumulative metres of coal seams, is a 3.2:1 strip ratio and has Newcastle spec coal. And there’s some 100Mt of this coal (in just the measured category).
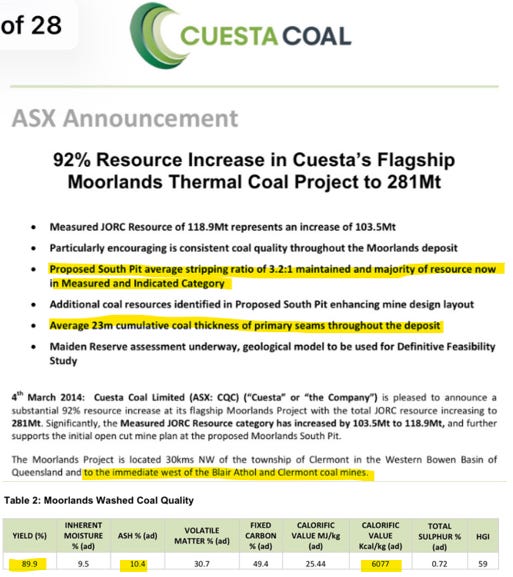
What does mining the low strip, high yielding, high quality coal at Moorlands look like economically versus Blair Athol’s current operations? My guess is something like the below…
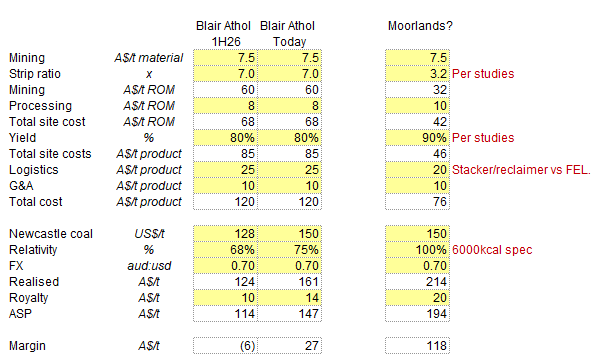
Now there may be some extra mayo thrown on the above numbers but even if you’re a bit more conservative Moorlands is going to generate something in the order of A$80/t more margin than what they are currently doing. And whilst the wash plant is restricted at ~350tph (~3mtpa) there is potential to bypass the wash plant with some seams at Moorlands given their thickness and take the combined BA + Moorlands operation well north of 3mtpa. Much of the infrastructure including the TLO currently used by Clermont has capacity to take well north of 10mtpa. Maybe Terracom could even repurpose the ~15km of overland conveyor from Clermont to Blair Athol and extend it from Moorlands to Blair Athol?
Who knows… but if you’re selling 2mtpa attributable at say A$100/t margins… you’re generating A$200m pa… and the company is priced at A$125m today. The opportunity seems large.
So what needs to be done here? Well firstly Terracom and Wintime need to come to an agreement on the commercial terms for developing this mine. The company has previously guided to just a matter of months and very small amounts of capital to develop this deposit given all the existing infrastructure. The regulatory process seems to be held up by a request for information.. you can see the up to date status of the application here.
Balance Sheet & Corporate Shenanigans
So far I hope I’ve made a fairly compelling case as to some hidden value at Terracom. It’s a high cost producer today and that gives you huge amounts of torque to the thermal coal price… but it also has some very underappreciated options over the next 18mths that could extract large amounts of value for shareholder… involving Moorlands, the purchase of infrastructure owned by Clermont (likely just for taking on the rehab obligations) and possibly the sale of the South African business now that the logistics is getting worked out.
But that value is only going to be unlocked and shared amongst all shareholders if both management and shareholders are aligned. And this is the interesting piece.
Indonesian entity Orbit Marketing held zero Terracom stock a year ago (in fact the entity didn’t even exist) and today owns 45%. It did this in two moves… first the acquisition of 19.98% stake via a block trade with an undisclosed offshore vehicle on the 17th of December 2025… and then by underwriting the 1.25-for-1 AUD60 million dollar rights issue that occurred just six days later (two days before Christmas when everyone was on holidays). Orbit got A$40m of the A$60m raise and so went from effectively zero stock to 45% ownership in a matter of a couple of weeks.
And this rights issue wasn’t without controversy.. with the AFR claiming many shareholders oversubscribed for stock but were refunded and the stock issued to Orbit instead. Take a read of the AFR article here.
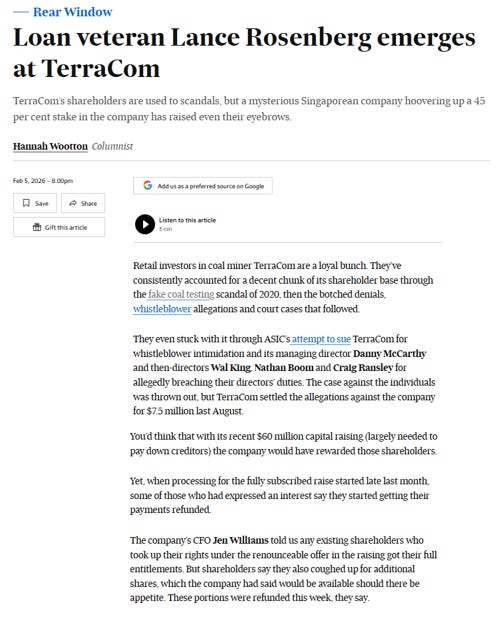
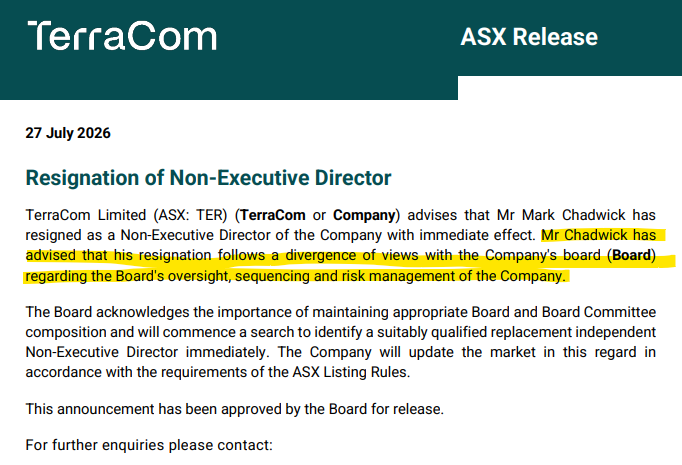
After Orbit secured a 45% holding in Terracom in early January following the recapitalisation we saw heavy movement in the board and management of the company. Incumbent directors Mark Lochtenbery, Glen Lewis and Mark Ludski all left and not long after followed the departure of CEO Danny McCarthy and CFO Jen Williams… it was a mass exodus. Appointed to replace the directors that left were Andy Coles, Stephen Barber and Mark Chadwick… but the latter only lasted a couple of months in the position and had this to say on his departure…
And this brings me to the balance sheet… where Terracom released their 30-Jun financials after the market closed on Monday 31st of August.. two minutes before the ASX deadline.
What was in the financial report wasn’t all that surprising. They told us they were low on cash (just A$8m in the bank!) previously with the quarterly report published late July… they also had previously disclosed that production was running behind schedule due to weather and that they had put in a new truck and excavator fleet to chase 2.0-2.2mt in FY27 at Blair Athol (up from 1.5mt in FY26).
But they also published that night with their 30-Jun accounts a separate “Market Update”… where they basically describe operations as a mess, the companies financial condition precarious… and that they will all but need to do an equity raising (but decided not to do one then and there).
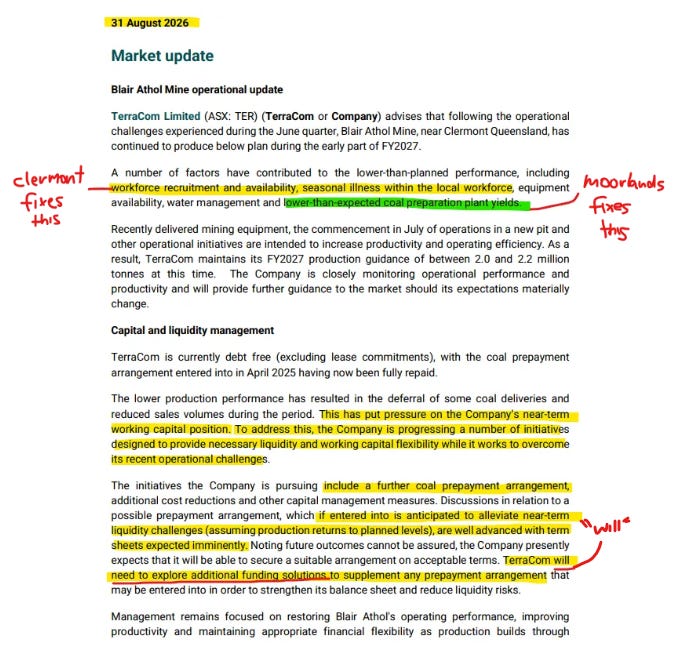
Now I’m not privy to the companies financial situation outside of the 30 June accounts but the declaration the company will need to do additional funding above a prepayment seemed a little premature to me… and if it wasn’t why not do the raise then and there rather than spooking the market and seeing your equity fall 15% the next day?
Newcastle coal prices are north of US$140 per tonne. Last year the company did a prepayment for A$40m (fully repaid). Operating expenses at Blair Athol average around A$15m per month… and creditors had fallen from A$56m at 31-Dec to A$36m at 30-Jun. To me it seemed there were far more levers the company could pull without using this language… even the South African business should be able to fund itself and some.
Call me a conspiracy theorist but my only thought is the company will look to do another distressed rights issue like that in January (done at a 26% discount) where Orbit will underwrite the rights issue.. hope a bunch of shareholders don’t take up their rights.. and go from 45% to somewhere north of 50% and have a controlling stake. Then they can mop up the remaining minorities and take Terracom private before the big rerate occurs as the Moorlands and Clermont deals (plus Sth African sale) are all executed over the following months.
Maybe that’s complete paranoia of being a minority shareholder (especially if you look at what’s going on at CAY.AX today with major shareholder trying to pull one over minorities)…
Summary
Coal is making a strong move the past few weeks on the back of material Chinese supply cuts, a force majeure at Qatari LNG and the Northern Hemisphere picking up buying ahead of winter.
When looking for resource investments I like to find plays in commodities I like but that have some hidden value and aren’t completely reliant on the underlying commodity price going north. Terracom in addition to having torque being a very high cost producer at the moment has some hidden value given the significant infrastructure it sits on, the closure of the neighbouring mine which could add to that infrastructure and a unmined coal deposit some 15km away that looks highly economic compared to what it is currently mining.
But there seems to be real risk that the major shareholder may not be willing to share the inherent value of the Assets the company sits on with all shareholders. And I wouldn’t be surprised if a similar underwritten recap tactic like that done in December which took Orbit from 20% to 45% were to play out again.
As a degenerate I own a small position, am still conducting some further DD and am just more intrigued as to how this will play out.
As always - not investment advice.. and there’s a good chance much of the information I shared above is factually incorrect.. so do your own due diligence!
Respeculator
**Disclaimer - this is NOT intended as financial advice - before acting on any information, you should consider the appropriateness of the information provided to your financial situation and seek advice. Whilst every effort is made to ensure the accuracy of data provided there’s a good chance inaccuracies exist. This is opinion only.**
Let’s fucking go you huge balled degenerate 🕺❤️
Great write up on Terracom. Assets look great in a coal bull market and intriguing set up with Moorlands/Clearmont. But there’s the old saying that if you lie down with dogs you come up with fleas. Yes agree it’s a good idea to own stocks which don’t purely rely on a bull market in their commodity. But on the other hand the set up for coal going towards winter looks so good that you would hate to get the coal call right and then discover that you are sat in a losing position because you gambled that a pack of hyenas wouldn’t bite you. Maybe best to have some solid positions in the obvious contenders and have this one as a side flutter which won’t spoil your coal party if it blows up in your face but could potentially just add a nice touch of icing on top of a nice cake.