

I provided an update last week on a few trades I have made since resurrecting this blog (read here). This is an update on the update… for a few news releases that occurred this week.
1. Aussie Refiners
See note A crack-up boom
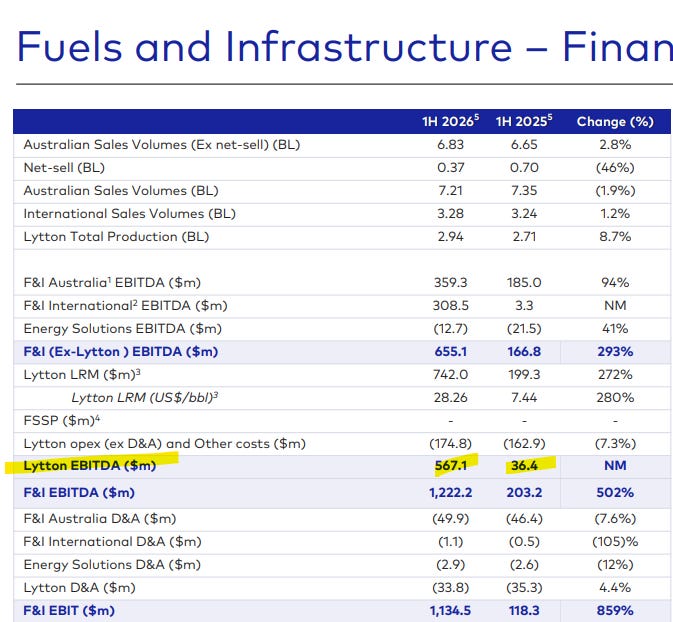
Both Ampol (ALD.AX) and Viva (VEA.AX) reported earlier this week. Both reported solid results and are returning good dividends to go with the earnings uplift. I’ll highlight two slides below from Ampol, the first shows the refining margin yoy movement showing the torque the refining business has to the movement in crack spreads.
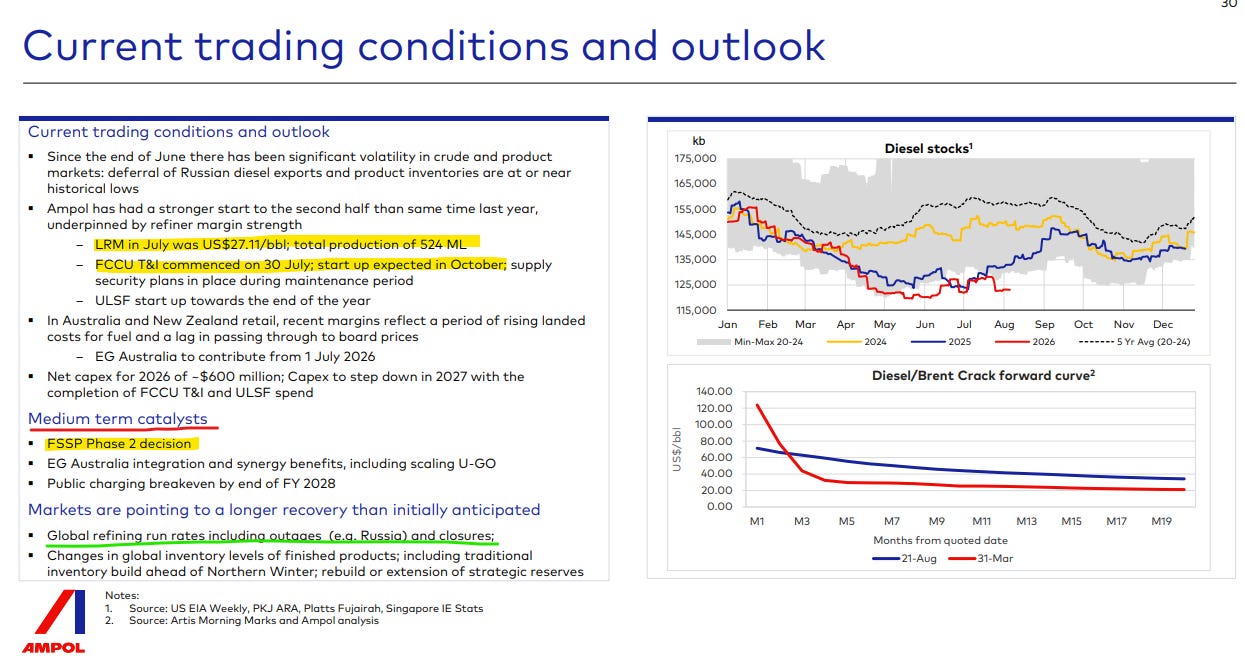
The second highlights the situation as it stands currently where cracks are expected to stay “higher for longer” given the refinery outages. Ampol also flag a key catalyst for refiners being the Aussie government FPPS (Fuel Security Services Payment) Phase 2 decision expected in the second half - which is the payment the Aussie government will make to underwrite profitability of these now ‘strategic infrastructure’ Assets.
I’m inclined to move on from this trade but will sit and think on it for a few days. On the one hand the refining capacity shortage does look like it will extend for some time and you have directors buying stock post results (small amounts) but on the other hand the price of both companies has rerated meaningfully and the market has a habit of resolving these issues. What the orange man does could have a big impact on non-US refiners too….

2. Aurelia Metals
(notes: “The Cobar Comeback... Pt 2” and “Addendum: Aurelia Metals”)
I said last week I was watching results from both Aurelia and Harmony Gold this week to see if any corporate action was in play between the two. Aurelia announced a new CEO appointment on Tuesday and both Aurelia and Harmony published financials Thursday. It’s clear by the CEO appointment and results announcements that corporate activity won’t happen any time soon.. but a couple of thoughts…
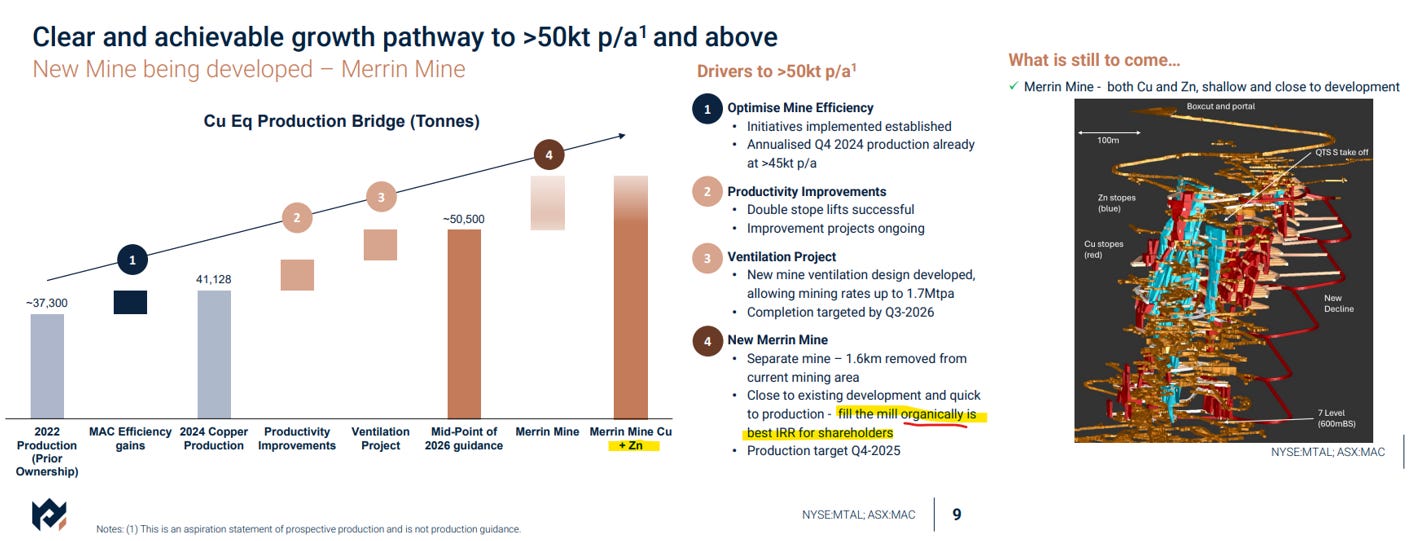
The slide below shows the prior owners plan for the CSA Copper mine… looking to lift CuEq production >50ktpa by going after some shallow copper and zinc mineralisation to add to the deeper higher grade copper lodes to ‘fill the mill’.
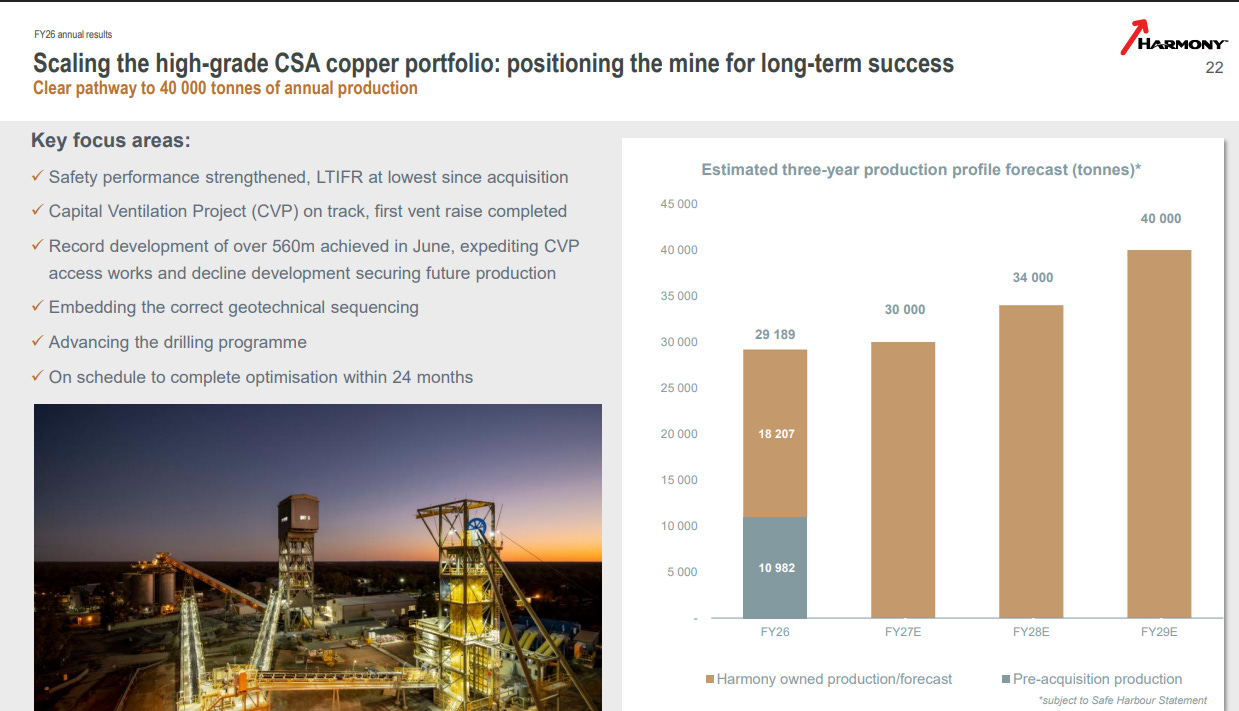
Now look at Harmony’s plan… to run at 30ktpa in FY27 and gradually step up to 40ktpa over a couple of years as they put in the deeper ventilation to help improve productivity of the lower levels of the mine. Seems rather unambitious.
I’m still of the belief these two neighbouring Assets belong together for all the reasons I outline in the initial thesis. But for whatever reason we are not going to see that in the short term and Harmony will continue running their mill at ~50% capacity and leaving those shallow copper and zinc ores in the ground. Given the rectifications they have had to make to the mine and mine plan since acquisition perhaps they need more time to understand the local geology and workforce etc before committing any more capital in the region.
Aurelia’s results were solid but nothing special. Below is the estimates I provided in the initial note with the red highlighted column out to the right the now company guidance for FY27.
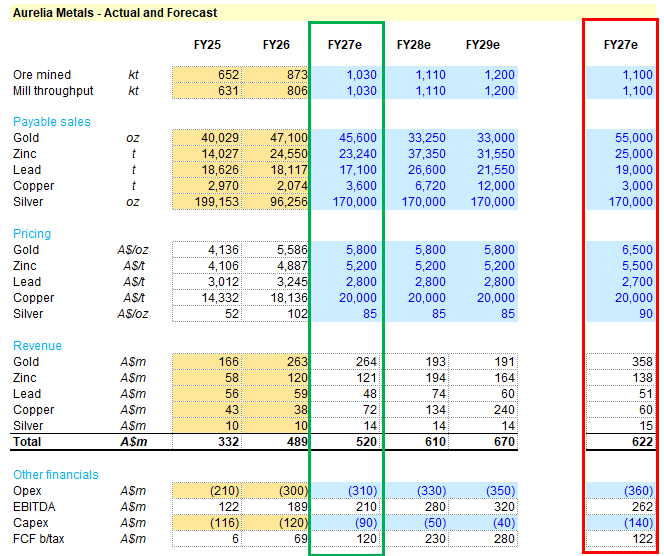
Opex and capex are materially higher but this is offset by increased gold and zinc production along with higher prices. While the magnitude of the cost inflation was above expectations you do need to factor in price linked costs (ie royalties), higher diesel prices, and the increased production. The company is also spending some added capital on the Peak South shaft given what the company sees as an extended mine life there now - which isn’t a bad thing.
At A$700m MCAP, A$550m EV the company is trading at 2.9x trailing EV/EBITDA and 2.0x forward EV/EBITDA… but as I discussed in the initial note the trick with these smaller mines is how much of this EBITDA needs to be recycled into opening up new orebodies to sustain production rates. My view is that capex will drop away for some time as they open up the new Great Cobar mine - but the drill bit will determine the longevity of the main orebodies this year.
I sold a third of my position given the corporate activity is now pushed back and the stock has run ~65% in the past month.. I’ll hold the remainder as I think it’s still cheap and there’s a big inflection in cash flow and no doubt shareholder returns incoming over the next 12months (the company just reinstated dividends after a 6 year absence). And with any luck we will see some corporate action… eventually.
As I said in the initial note - director Lyn Brazil has had the habit of opening his wallet and buying large parcels of stock on market after results for the past few years. It will be interesting to see if he does so again this year… he’ll have some dividend proceeds after all.
3. 29 Metals
(notes: “Sink or Stream”)
My thesis on the near term set up for 29 Metals was that covenant breaches on the 30 June accounts would force them into a refinancing and that even though the company wasn’t in the strongest negotiating position that there was some non-dilutive financing options available to 29M that could solve the balance sheet issues and rerate the stock. A reminder of what I wrote below:
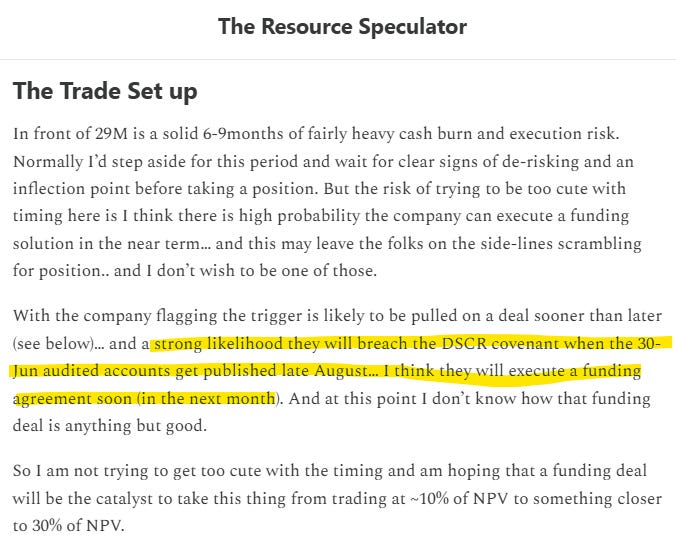
Well… the company did in fact breach its DSCR (and NTLR) covenants… but they received a waiver from the lenders.
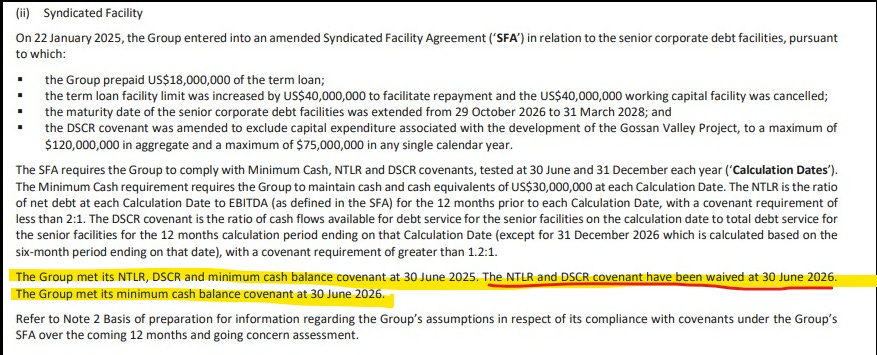
One would assume the company would have had to have given lenders some comfort that their financial position was going to be repaired and there was no material increase in risk to the lenders position (recall the company was forced into an equity raise not long after 31-Dec accounts). The company also outlines below that it has environmental bonding guarantee facilities expiring on the 29th of October that require renegotiation in addition to the wider group financing facilities.
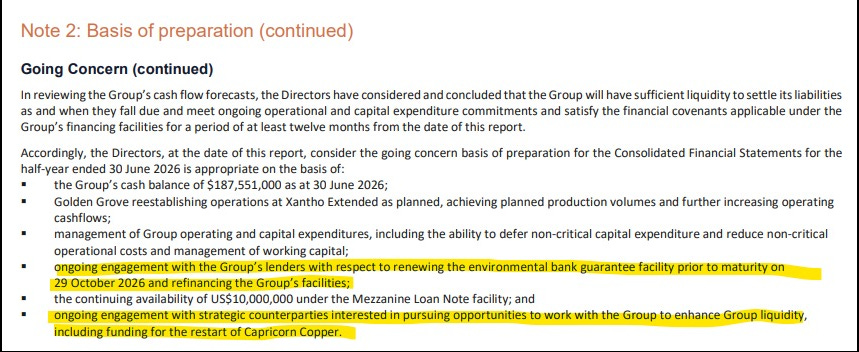
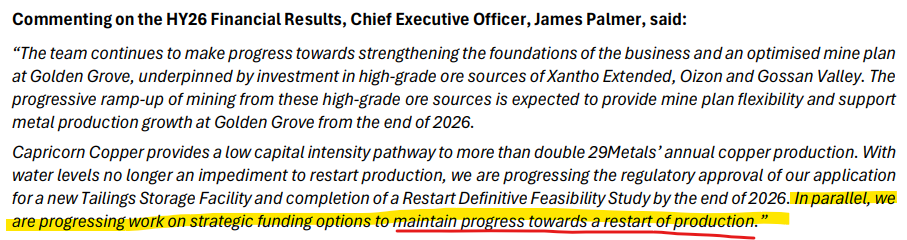
And here is the CEO commenting that they are working on funding options to “maintain progress toward a restart of production”. This is a key change of language in that previously they said they were looking at financing options to fully fund the restart of Capricorn Copper… now they are looking at options to maintain progress toward a restart of production. This change in language above makes it feel like they won’t be waiting around for Capricorn permits before executing a funding solution and that it may be imminent.
My view here hasn’t changed and that they will be able to execute on a non-dilutive financing in the near term. The uplift in copper, zinc and precious metal prices recently have helped their negotiating position. And while my thesis is yet to play out and the stock has rerated some ~40% on the back of general sector sentiment I am still willing to hold the stock here given everything looks on track operationally and my belief that a funding solution could see this rerate to something closer to 60cps.
4. South32
(notes: “Capturing the Arb”)
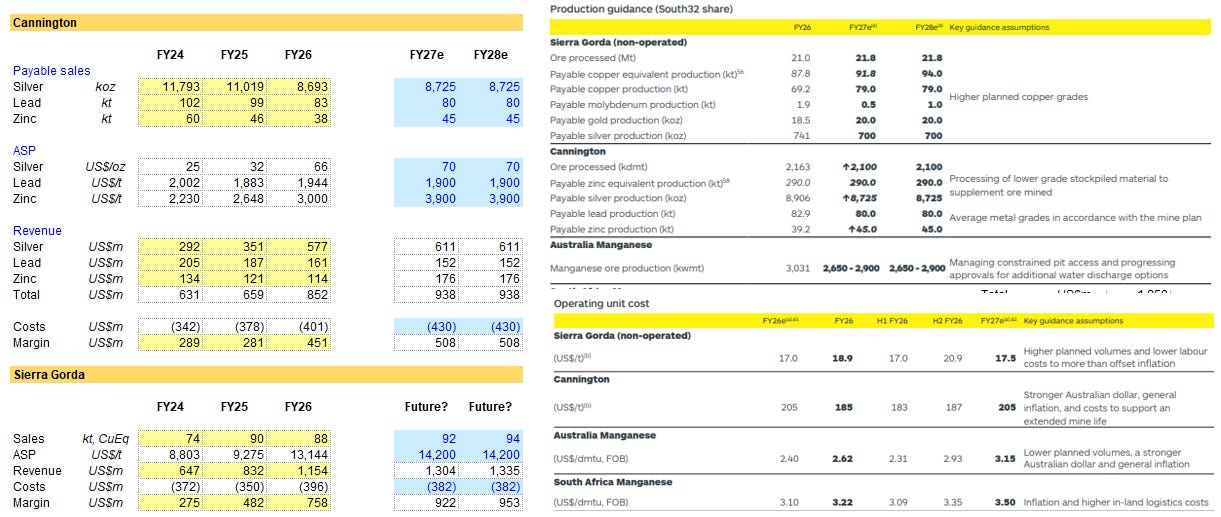
South32 results were solid. The stock is at all time highs today with a ~US$16.5bn market capitalisation and a ~US$15.5bn enterprise value. The pending transactions (in Aluminium, Coal and likely Manganese) I think places the proforma “CleanCo” at around US$9.5bn EV. My math below based on the companies guidance says the two key Assets will generate ~US$1.4bn in FY27 which places the company around 6.8x EV/EBITDA.
This is in line with peers and not “cheap”. I guess the question is how much value of the US$9.5bn do you give Hermosa where US$4bn has been expended to date and will generate near US$1bn pa for 35yrs+… and also what will happen with the proceeds of the Alcoa transaction. Listening to the conference call it seems the company is in pursuit of growth.
I’m going to trim my position here.. the key commodities the company mines (copper, zinc, silver) are all flying and I think the company will be much sought after in ~6mths once the Alcoa deal is closed or more likely in ~18mths once the Hermosa project is online. I may keep a core position because of this… but the stock has rerated meaningfully especially when you consider half the company was “cash” or cash in waiting… so a 20% move on the MCAP is really a 40%+ move on the non cash Assets. I’m also less convinced shareholders will receive meaningful returns of the Alcoa proceeds which isn’t necessarily a bad thing but managements deal capabilities are tbd (I was impressed with new CEO on the conference call).
As always - this is just what I’m doing.. not financial advice.. seek it.
Best
Respeculator
**Disclaimer - this is NOT intended as financial advice - before acting on any information, you should consider the appropriateness of the information provided to your financial situation and seek advice. Whilst every effort is made to ensure the accuracy of data provided there’s a good chance inaccuracies exist. This is opinion only.**
Top class, thank you.
This is awesome. Thanks 🙏